
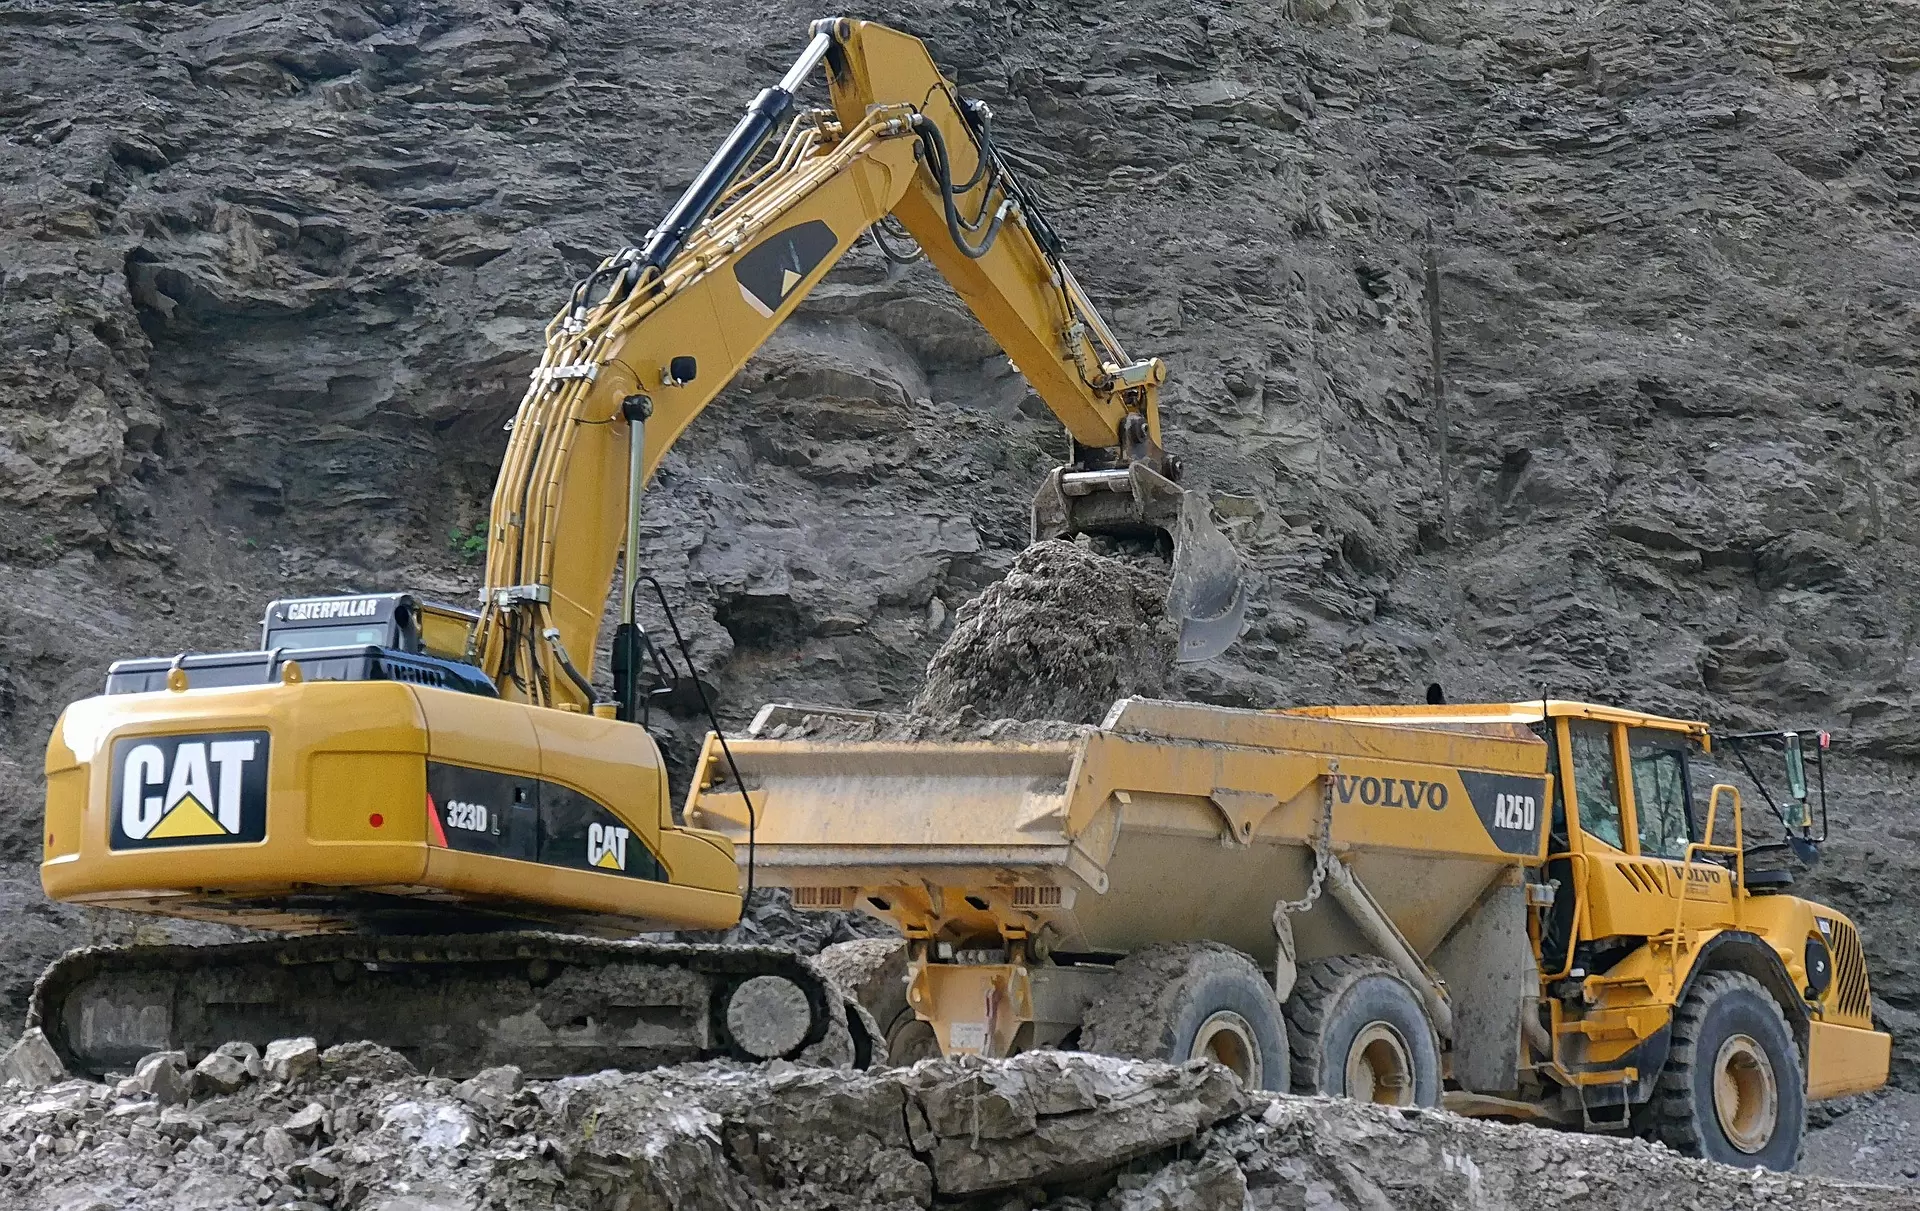
The excavator is the machine most owner-operators buy first, and the one most civil businesses buy most often. It’s also the purchase where the finance question gets asked at the worst possible moment, standing in front of a machine at an auction with a number in your head. This guide covers how excavator finance works in Australia, what lenders look at, and the specific situation of buying your first machine.
Machine sizes and who buys them
- Mini excavators, roughly one to two tonne. Landscapers, plumbers, pool and fencing contractors. Small enough to tow behind a ute and fit through a side gate, which is exactly why they earn.
- Two to five tonne. The workhorse range for residential work, trenching and small civil.
- Five to fourteen tonne. Civil contractors, subdivisions, drainage, road works.
- Fourteen tonne and up. Bulk earthworks, quarry and larger civil projects.
Skid steers, posi-tracks, dozers and loaders finance on the same principles, and our earthmoving, plant and construction equipment finance page covers the wider yellow goods category.
Financing your first machine
This is the most common excavator finance conversation there is: someone has been operating on wages, has work lined up, and wants to buy a machine and go out on their own. It’s also the hardest version of the application, because the business has little or no trading history.
What helps:
- A contract, letter of intent or clear work pipeline from someone who will engage you. Some lenders will weigh this heavily for a first machine.
- Industry experience. Years of operating the same machine type for an employer is meaningful, and it’s worth putting in writing rather than assuming the lender infers it.
- A deposit or a trade-in. It reduces the lender’s exposure and widens the options considerably.
- A clean personal credit file, since a new business is assessed largely on the person behind it. Our guide to your credit file explains what lenders see.
- Registering the ABN and GST before you apply, not during.
What doesn’t help is applying to several lenders at once to see who says yes. Each application marks your file. Getting matched to a lender that writes new-business plant deals, then applying once, is a materially better approach.
Ready to get started?
Book a chat with an Asset Finance Broker at Treadgold Finance today.
Hours, age and condition
Excavators are valued on hours as much as years. A machine with modest hours for its age and a documented service history is straightforward security; one with heavy hours and no records is not, regardless of how it looks.
Lenders pay attention to:
- Hours against age, and whether the two are consistent
- Undercarriage condition, which is the expensive part to put right
- Service records, ideally with the machine
- Brand and parts support in Australia, because resale is what the lender relies on
- Attachments included, which add to the value and can be financed with the machine
Older machines usually mean a shorter maximum term rather than a decline.
Attachments, hitches and the float
Two practical points that get left out of the budget:
Attachments. Buckets, a tilt hitch, an auger, a hammer or a grab often cost a meaningful share of what the machine does, and they can generally be financed with it. Bundle them into the one facility rather than going back for a second approval.
Getting it to site. A machine you can’t move doesn’t earn. Small excavators travel on a plant trailer behind a ute; larger ones need a float or a tilt tray. If you’re buying the trailer at the same time, it can often go on the same facility, which we’ve covered on our trailer finance page.
Where people buy
Dealers, with clear title, an invoice and often warranty or a service package. The simplest path, particularly for a first machine.
Auctions, which move a lot of excavators and reward preparation. You bid without knowing the final price and settle quickly, so get pre-approved before the sale and know your ceiling.
Ex-rental and ex-fleet machines. Often well maintained with full service records, though usually with solid hours. Frequently good value and readily financed.
Private sales, where the register check matters: search the Personal Property Securities Register against the machine’s serial number to confirm nothing is owing before you pay. Any existing finance is paid out at settlement and the interest released. The same register covers plant, and you can search it yourself at ppsr.gov.au.
Imports are possible but add compliance, timing and payment complications, and not every lender will fund one.
Buy or keep hiring?
Dry hire suits work that comes and goes. Ownership makes sense once the machine is working consistently enough that hire costs exceed what a repayment would be, and once you want the asset on the books. If you’ve been dry hiring the same machine and want to buy it out, that purchase can generally be financed like any other, though it’s worth establishing what your hire payments have contributed toward the price before agreeing a figure.
The structures used
Chattel mortgage is the usual choice for a business buying a machine to keep: you own it from day one, the lender registers a security interest. See chattel mortgages explained. Finance lease and hire purchase are alternatives where ownership timing or tax treatment suits better; see finance lease versus hire purchase. Rental suits a defined project.
If you can’t provide full financials, which is normal for a newer operation, low doc business loans are assessed on bank statements, BAS or an accountant’s declaration; who qualifies for a low doc business loan sets out the criteria.
The tax side
An excavator bought for business use generally attracts deductions for depreciation and for the interest component of the finance, and in some years an immediate write-off applies to eligible assets under a threshold, tested against the machine’s total cost rather than the business-use share. We’ve explained the mechanism in how the instant asset write-off works. Confirm with your accountant before timing a purchase around it.
Where a broker fits
Lender appetite on excavators varies most on two things: machine age and hours, and whether a business with little trading history can be approved on the strength of a contract and the operator’s experience. Those are exactly the deals that get declined by the wrong lender and approved by the right one. Our equipment finance page sets out what we arrange, Australia-wide.
This article is general information only and is not financial, tax or legal advice. Lender criteria vary and change; confirm the tax treatment of any purchase with your accountant.
Damo Treadgold is the director of Treadgold Finance, an FBAA-accredited finance broker on the Sunshine Coast, arranging equipment, machinery, vehicle and business finance Australia-wide.
Frequently Asked Questions
Can you finance an excavator?
Yes. Excavators are financed routinely, secured against the machine, usually as a chattel mortgage, finance lease, hire purchase or rental. New, used, ex-rental and auction purchases are all common.
Can I finance my first machine if I’m just starting out?
Often yes. A contract or work pipeline, documented industry experience, a deposit or trade-in, and a clean personal credit file all help. Apply once through a lender that writes new-business plant deals rather than applying to several at once.
Do hours matter more than age on an excavator?
Both count, and hours usually count more. Hours consistent with the age, a documented service history and sound undercarriage make a machine much easier to finance.
Can attachments be financed with the machine?
Usually yes. Buckets, hitches, augers, hammers and grabs can be bundled into the same facility. Mention them at the start so it’s one approval.
Can I finance an excavator bought at auction?
Yes, with pre-approval arranged first. Auctions settle quickly and you bid without knowing the final price, so knowing your limit beforehand is essential.
Can I buy out an excavator I’ve been dry hiring?
Generally yes, and it can be financed like any other purchase. Establish what the hire payments have contributed toward the price before agreeing a figure.





