
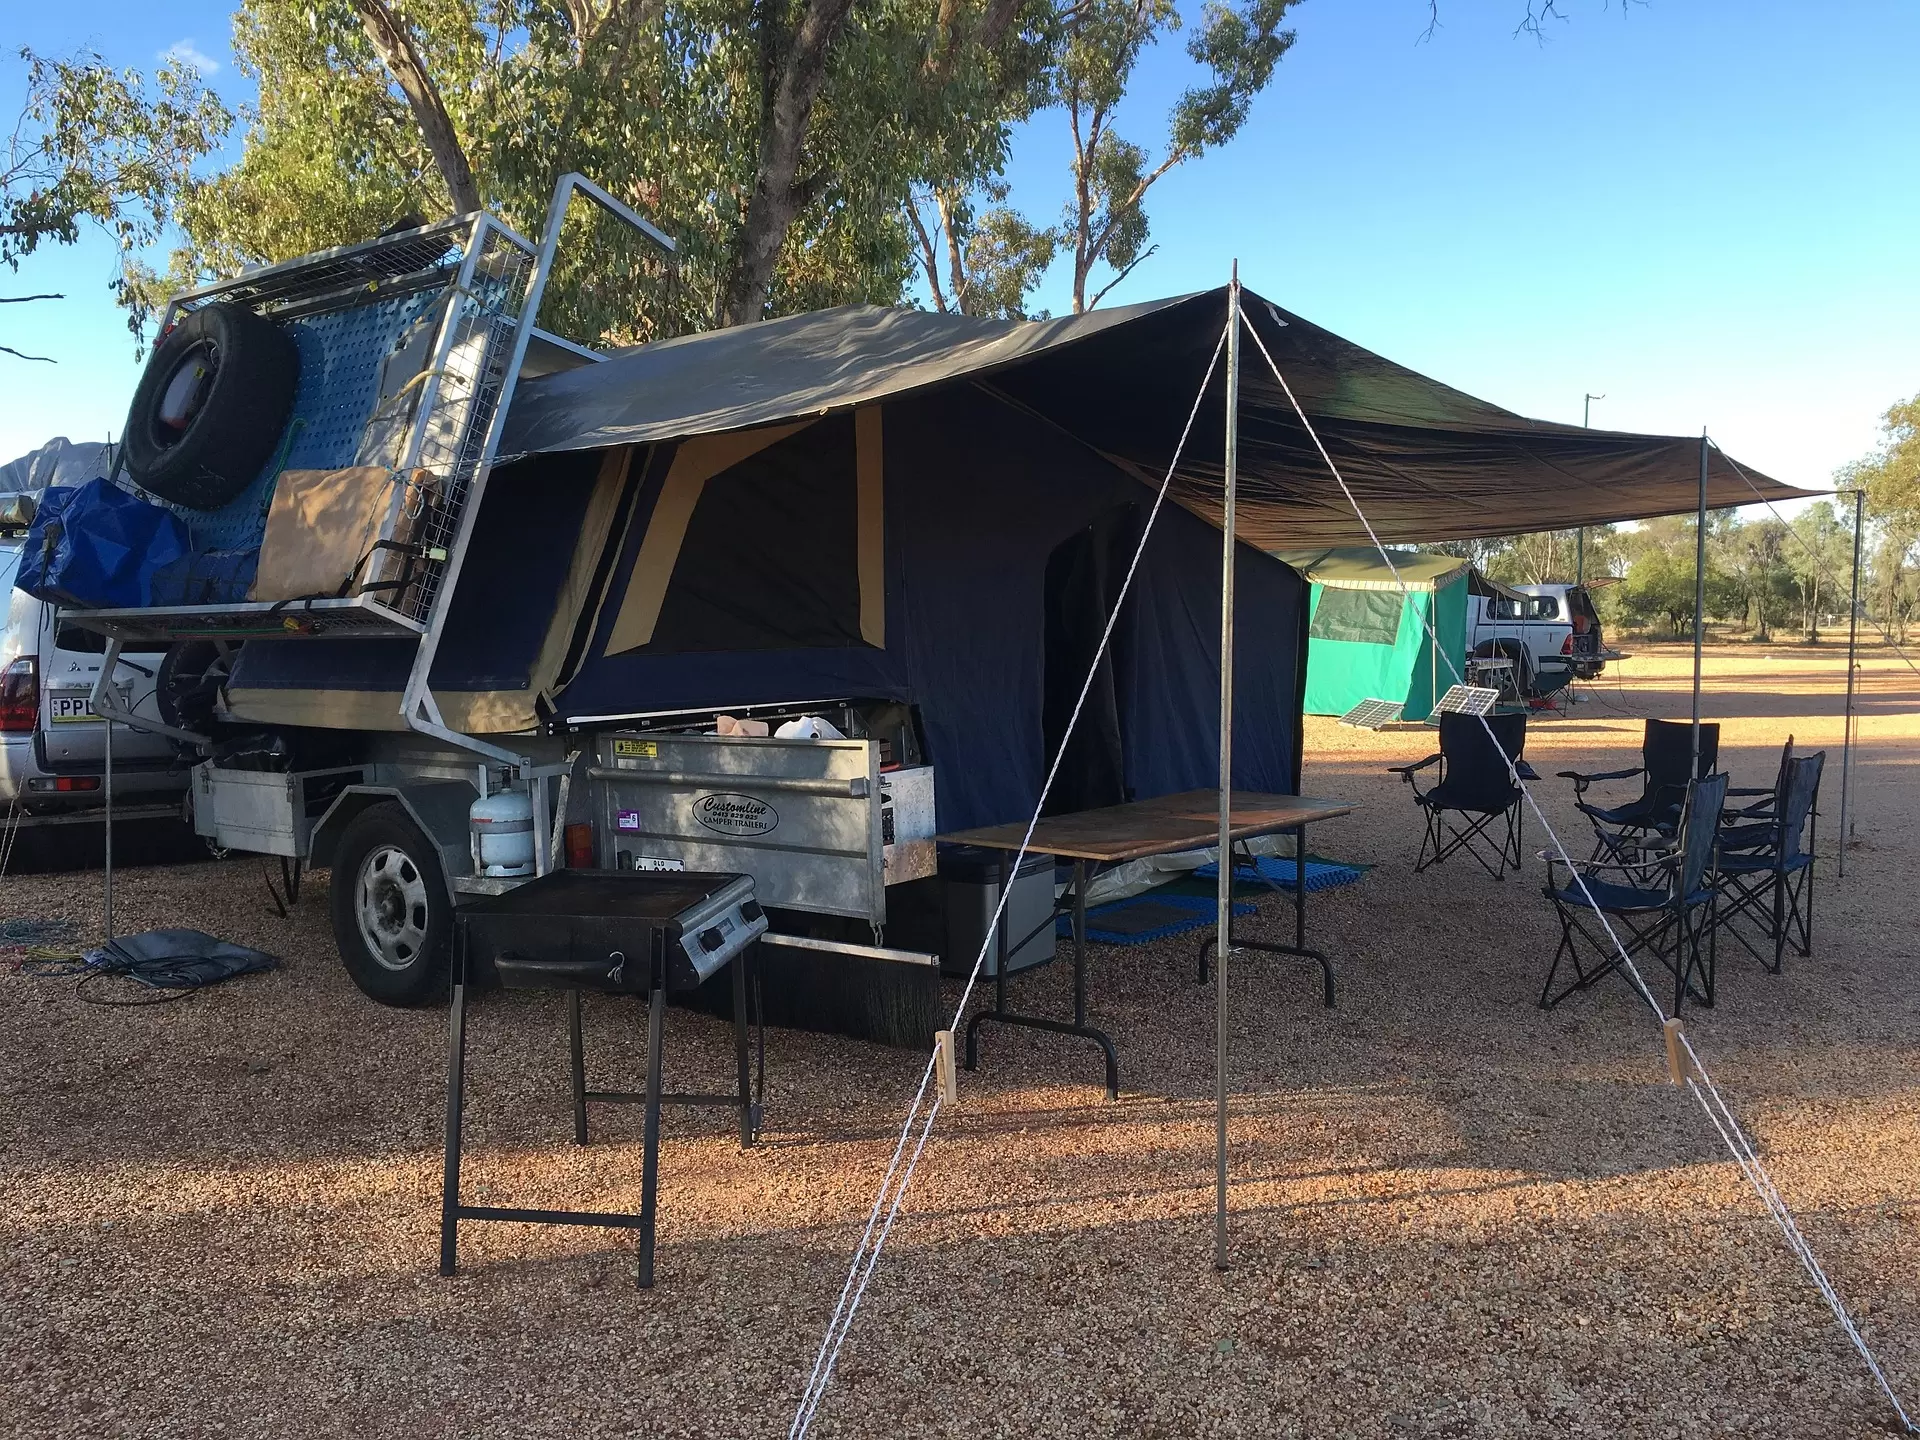
Camper trailers sit in an awkward spot for finance. They cost more than most people want to put on a credit card and less than lenders are always keen to write a secured loan against. That doesn't stop them being financed, but it does decide which lenders will do it and how. Here's how camper trailer finance works in Australia.
What gets financed
- Soft floor and hard floor camper trailers
- Forward fold and rear fold designs
- Hybrid campers, the enclosed caravan-style units on off-road chassis
- Off-road and touring campers with independent suspension
- Roof top tents and ute canopies where they form part of a larger purchase
Caravans, pop-tops and motorhomes follow similar principles; our caravan loans page covers those.
The minimum loan amount
The most common obstacle, and it catches people who assume a knock-back is about them.
Plenty of lenders set a minimum finance amount. A well-priced used camper can fall below it, which means the question isn't whether you qualify, it's whether the lender writes loans that small at all. Fewer do at the lower end, and those that do have their own criteria.
Three ways round it: check before you commit to a particular camper, look at whether the setup costs belong in the same loan (below), or accept that a smaller purchase may suit an unsecured personal loan instead of a secured one.
Secured or unsecured
A secured loan uses the camper as security, with the lender registering an interest over it. Lower risk for the lender, generally the better structure where the camper's value and age support it. Our guide to secured car loans explains how security works; the same principles apply here.
An unsecured personal loan isn't tied to the camper. Common for older or cheaper units where the lender isn't relying on the asset's value, and priced accordingly for the higher risk.
Which applies is usually decided by the camper's value, age and registration status rather than by preference. An unregistered trailer, or one without a compliance plate, is harder to finance because the security is harder to value and resell.
Ready to get started?
Book a chat with an Asset Finance Broker at Treadgold Finance today.
Buying at a caravan and camping show
Shows are where a large share of campers are sold, and they're built to create urgency: show-only pricing, stock on the floor, deals that close before you leave the gate.
That's exactly the situation where finance goes wrong. People commit on the day, then discover the loan doesn't come together, or accept whatever finance is offered at the stand because it's the only option in front of them.
Get pre-approved before you go. Two things follow from it. You know your ceiling, so you're negotiating rather than hoping. And you can treat the stand's finance offer as one option to compare rather than the only way to get the camper home. Our guide to pre-approval explains how it works, and dealer finance versus a broker or bank covers why comparing matters even when the on-the-spot offer looks fine.
Used campers and private sales
Camper trailers hold value reasonably well and the used market is active, so financing a second-hand unit is routine.
Age matters at the end of the term, not the start. Lenders cap how old an asset can be when the loan finishes, so an older camper usually means a shorter maximum term rather than a refusal. Shorter term, higher repayments, which is the practical constraint.
On a private sale, search the Personal Property Securities Register against the camper's VIN before you pay, at ppsr.gov.au. If money is owing, the lender's interest follows the trailer to you unless it's paid out at settlement. Where the purchase is financed, the lender pays the seller directly once the checks are done, which protects both sides. We've set the process out in buying a car privately with finance.
The setup, and what can go in the loan
An annexe, solar panels, a lithium battery upgrade, a fridge, extra water tanks, recovery gear. The setup often runs to a serious share of what the camper cost.
Where those items appear on the dealer's invoice as part of the purchase, they can generally be financed with it. Bought separately afterwards from a different supplier, they usually can't be added later. If you want them financed, have them quoted on the same invoice from the start. That's also one way a purchase clears a lender's minimum amount.
The tow vehicle
Worth checking before you buy rather than after: the camper's loaded weight against your vehicle's towing capacity and the combination limits. An off-road hybrid weighs a great deal more than a soft floor.
If the camper means changing vehicles, the two purchases can sometimes be arranged together, which is simpler than two separate applications. Our car loans page covers the vehicle side, and trailer finance covers work trailers if that's the need instead.
What lenders assess
- Income and employment, and whether the repayments fit comfortably
- Credit history. Our guide to your credit file explains what lenders see
- The camper as security: age, condition, brand, registration status
- The amount, against the lender's minimum
- Any deposit, which widens the options
Most secured lenders also require comprehensive insurance from settlement, and it's worth getting a quote before you commit rather than after.
Where a broker fits
The two things that decide a camper trailer deal are the loan amount and the unit's age and registration, and lender appetite on both varies more than for cars. Knowing which lenders write smaller amounts, and which will take an older or unregistered trailer, saves an application that was never going to be approved. Our caravan loans page sets out what we arrange, Australia-wide.
This article is general information only and is not financial or legal advice. Lender criteria vary and change.
Damo Treadgold is the director of Treadgold Finance, an FBAA-accredited finance broker on the Sunshine Coast, arranging caravan, car, boat and equipment finance Australia-wide.
Frequently Asked Questions
Can you finance a camper trailer?
Yes. Camper trailers are financed either as a secured loan, using the camper as security, or as an unsecured personal loan where the unit's value, age or registration status doesn't support security.
Is there a minimum amount for camper trailer finance?
Many lenders set a minimum finance amount, and a cheaper used camper can fall below it. It's the most common obstacle in this category and it isn't a credit issue. Check before committing to a particular camper.
Can I finance a used camper trailer?
Yes. Lenders assess age, condition, brand and registration. The maximum age applies at the end of the loan term, not the start, so an older camper usually means a shorter term rather than a refusal.
Should I arrange finance before a caravan and camping show?
Yes. Shows are built around on-the-day decisions. Pre-approval means you know your limit before you walk in and can compare the stand's finance offer rather than accepting it by default.
Can I include the annexe, solar and fridge in the loan?
Usually, where they appear on the dealer's invoice as part of the purchase. Gear bought separately afterwards generally can't be added later.
Do I need to check the register before buying privately?
Yes. Search the Personal Property Securities Register against the camper's VIN before you pay. If finance is owing and isn't paid out at settlement, the lender's interest follows the trailer to you.





